May decline sits against a mixed activity picture
S&P Global’s monthly GDP estimate fell in May, making it one of the few output measures to show a decline that month. The estimate is subject to revision, and its drop sits alongside a broader set of indicators that offer a more mixed read on activity. That combination matters: one monthly estimate can flag a change in momentum, but it can’t settle whether the economy is broadly contracting or simply moving through a soft patch.
Monthly GDP estimates are designed to provide a more frequent view of economic activity than the official quarterly measure. That frequency can make them useful for tracking changes as they emerge, but it also means the series can be noisy and its readings can shift as more information becomes available. A decline in one month, then, deserves attention without being treated as a verdict.
The chart brings several different kinds of evidence together. Employment measures track labor-market conditions, industrial production follows factory and utility output, and income and sales measures capture other parts of the economy. These series don’t move in lockstep because they measure different activities and are compiled from different data. A split between them can be informative: it may show that weakness is concentrated, or that the indicators are capturing different parts of a changing economy.
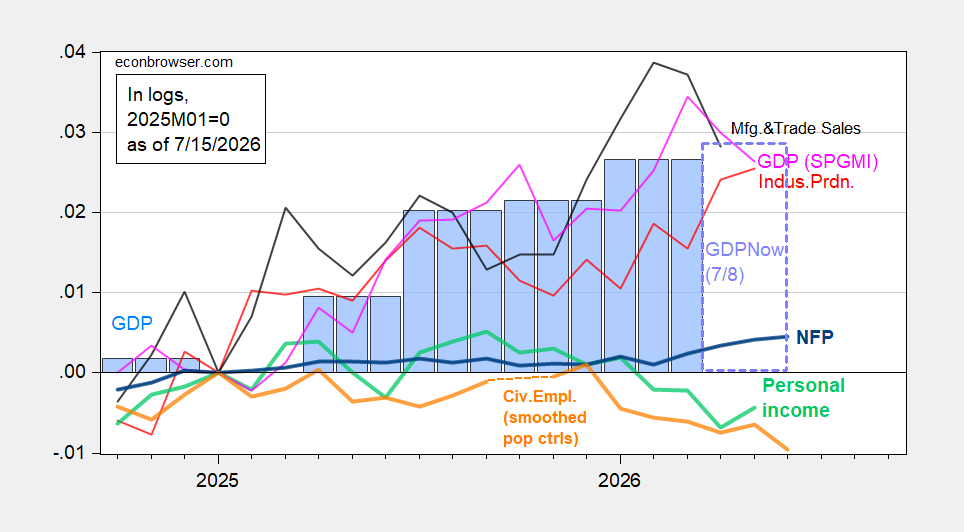
Figure 1: NFP employment (bold blue), civilian employment with smoothed population controls (bold orange), industrial production (red), personal income excluding current transfers in Ch.2017$ (bold light green), manufacturing and trade sales in Ch.2017$ (black), and monthly GDP in Ch.2017$ (pink), GDP (blue bars), GDPNow estimate (dashed blue line box), all log normalized to 2025M01=0. Source: BLS via FRED, BLS, Federal Reserve, BEA 2026Q1 3rd release, Atlanta Fed nowcast of 7/8, S&P Global Market Insights (nee Macroeconomic Advisers, IHS Markit) (7/1/2026 release), and author’s calculations.
Normalization gives the chart a common starting point, so readers can compare how the measures have changed relative to that base. It doesn’t make the series interchangeable, or turn their different definitions into one measure. The figure is best read as a set of cross-checks: whether the signals broadly reinforce one another, where they diverge, and whether a single monthly move is large enough to alter the overall picture.
This is more significant than it looks, but only as a caution. When a timely estimate weakens while other indicators give a less uniform signal, the useful question isn’t simply which line is right. It’s whether the decline persists, whether other measures begin to confirm it, and whether later revisions change the initial reading.
Q2 tracking remains positive
Comparing quarterly annualized growth rates puts the May decline in context. Monthly GDP is volatile, but its pattern remains consistent with GDPNow and S&P Global’s current estimate of 1.3% quarter-on-quarter annualized growth for Q2. That estimate points to expansion across the quarter, even with a monthly setback inside it.
Quarterly annualized growth translates a quarter’s change into a pace that would result if that rate continued for a full year. It’s a convention for comparing growth rates, not a claim that the same pace will persist. The measure can also make a modest change within one quarter look more dramatic when expressed at an annual rate, so the underlying period and the method matter.
The comparison in the second figure includes more than one monthly GDP series, alongside a coincident index and private nonfarm payrolls. Each offers a different lens on activity. Monthly GDP attempts to summarize output, payrolls track employment in a particular part of the labor market, and a coincident index combines indicators intended to reflect current conditions. Agreement across these measures would strengthen the case for a common reading; differences call for care in describing the trend.
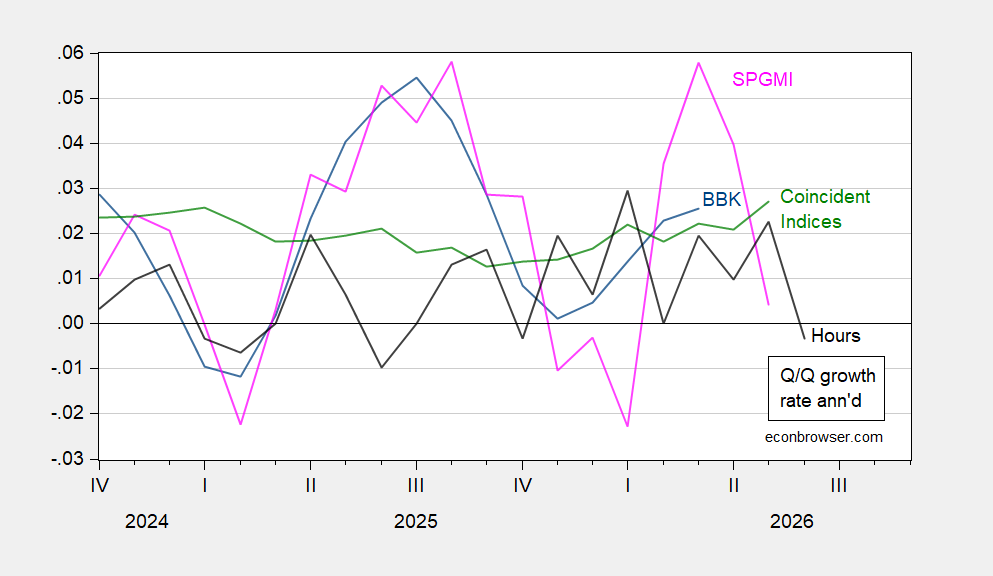
Figure 2: Quarter-on-quarter annualized growth rates for monthly GDP (pink), Brave-Butters-Kelley monthly GDP (blue), coincident index (green), and private nonfarm payroll (black). Source: IBRC, BLS, Philadelphia Fed via FRED, SPGMI and author’s calculations.
There’s a further limitation in comparing estimates: they can draw on overlapping information while still applying different methods. Similar measures often differ because they cover activity in different ways, incorporate data at different times, or revise their histories as source data improve. The figures therefore provide useful context, but they don’t remove uncertainty from the underlying estimates.
If you’re working in this space, the practical read is to keep the monthly decline in view while judging it against the broader set of measures and the quarter’s running estimates. A positive quarterly tracking figure doesn’t erase a weak month, just as one weak month doesn’t establish a contraction. The distinction is easy to lose when attention settles on the latest data point.
What the mixed signals imply
For now, the May decline is a cautionary signal within a volatile series, while the current Q2 tracking estimate still points to expansion. That’s a measured conclusion, not a clean all-clear: the quarterly estimate is current, the monthly reading can be revised, and the indicators don’t deliver a single uncontested account of activity.
The next useful test is whether subsequent observations reinforce the May weakness or pull the picture back toward the positive Q2 pace. Revisions will matter too, since they can change how the monthly movement fits into the quarterly record. And this is the part most people overlook: a disagreement among indicators can itself be a reason to wait for confirmation, rather than a reason to select the most dramatic reading.
For the moment, the evidence supports describing growth as positive in the current Q2 tracking estimate, with a notable monthly exception in May. The estimate could change. The signal remains unsettled.